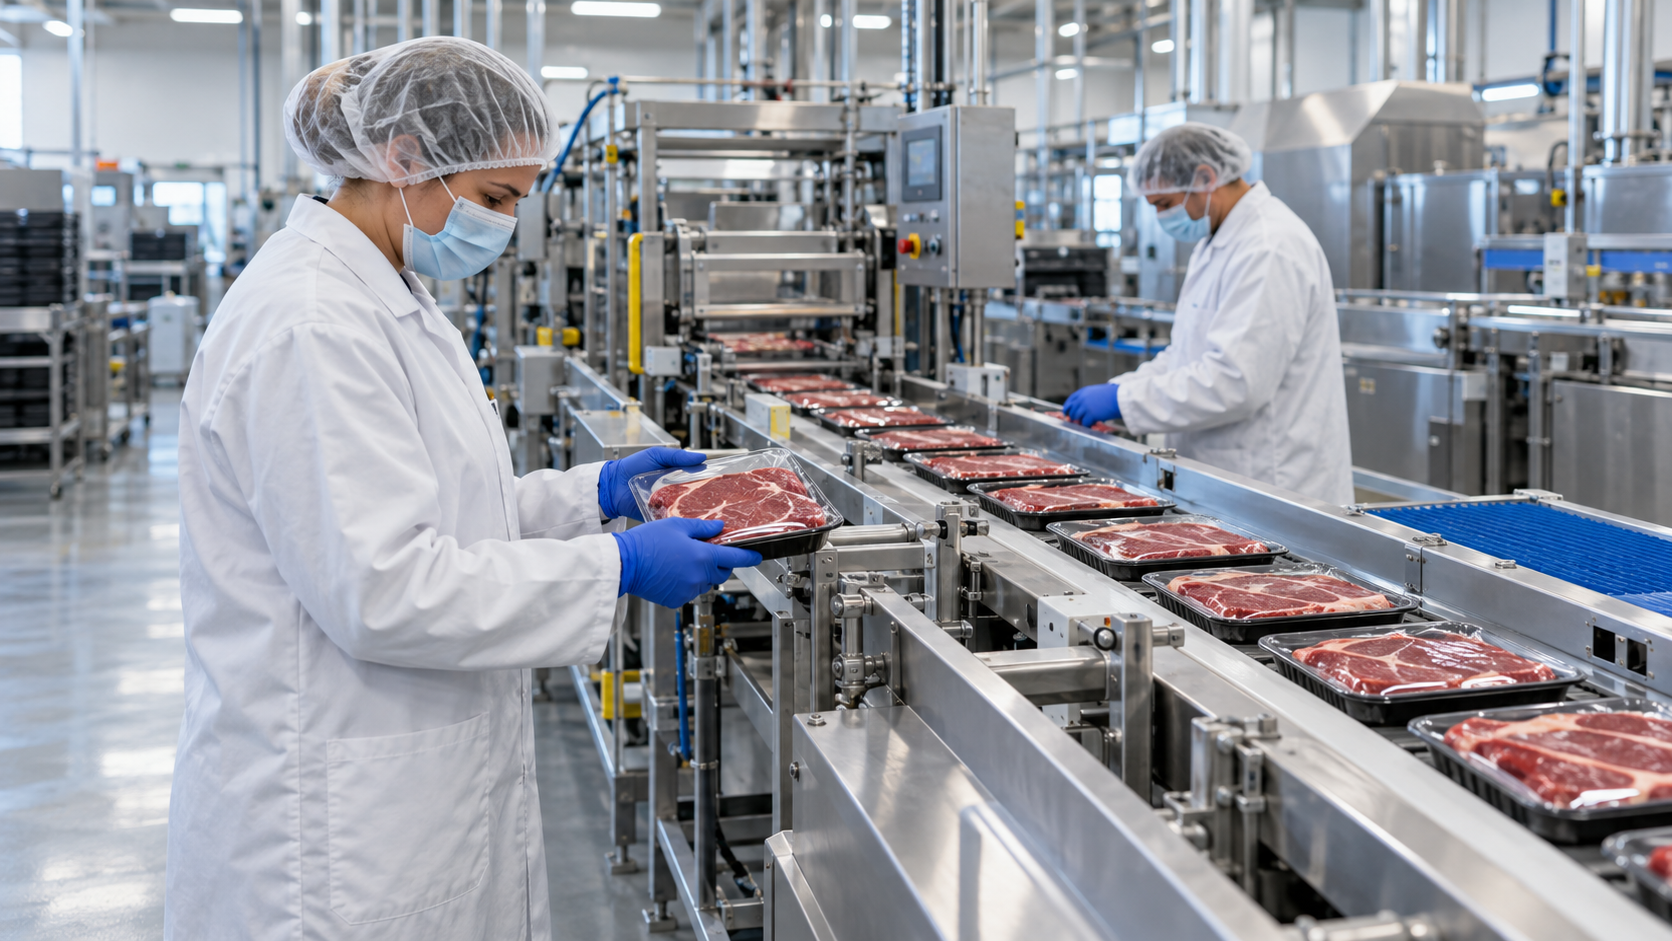
On October 23, 2026, USDA announced at least $5 billion in loan guarantee authority for the new Strengthening Processing for U.S. Ranchers (SPUR) program. The USDA SPUR loan program backs commercial loans to meat, poultry and seafood processors with a 90 percent federal guarantee, loans up to $175 million, and no rural area requirement. Yes, that's right: no rural requirement.
For processors that have struggled to finance new capacity, and for the lenders that serve them, SPUR is one of the most useful tools USDA has put on the table in years. Here is what the program does, who qualifies, what it costs, and why it deserves a close look.
SPUR is a USDA Rural Development loan guarantee program designed to add processing capacity and competition in meat, poultry and seafood. USDA describes the sector as particularly vulnerable to disruption, consolidation and concentration, and SPUR is intended to support independent and regional plants that diversify the supply chain.
The program came out of two executive orders. Executive Order 14424 directed USDA to create a guaranteed loan program for small and regional beef processors. Executive Order 14276 called for an America First Seafood Strategy, which is why seafood processing is included alongside beef, pork and poultry.
The legal authority is Section 1001(b)(4) of the American Rescue Plan Act, the same food supply chain resiliency authority USDA used for the Food Supply Chain Guaranteed Loan Program in 2021 and 2022. Loans are made and serviced under 7 CFR Part 5001, the OneRD guaranteed loan regulation, and USDA says SPUR is administered much like the Business & Industry (B&I) program, with a few changes for processors. Lenders that already know B&I will recognize the application, underwriting and servicing framework.
There is no rural requirement. USDA states that both urban and rural areas are eligible and that there are no geographic restrictions. The facility only has to be located and operated in the United States. This is one of the biggest differences from B&I, where the project generally must be located in an eligible rural area. A processing plant on the edge of Oklahoma City or Dallas can qualify just as well as one in a town of 3,000.
Any individual or entity engaged, or proposing to engage, in meat, poultry or seafood processing may be eligible, including:
Every borrower must operate under a USDA FSIS grant of inspection, a Cooperative Interstate Shipment (CIS) inspection, or an equivalent state inspection program. The business must be domestically owned, with a majority of owners who are U.S. citizens. Start-ups proposing to build a plant are eligible, as are existing operators.
SPUR covers nearly every major capital need a processor may have. Eligible uses include, but are not limited to:
Borrowers must show that loan funds will stay in the United States and that the project will create new jobs or save existing jobs for U.S. residents.
Processing plants are expensive to build, slow to ramp up, and often operate on thin margins. Those three traits are exactly why many banks shy away from them, and SPUR is aimed squarely at each one.
Every SPUR loan carries a 90 percent guarantee, leaving the lender with as little as 10 percent of the risk. B&I loans generally carry an 80 percent guarantee. The earlier Food Supply Chain Guaranteed Loan Program offered 90 percent only on certain fixed-rate loans, while SPUR applies the 90 percent guarantee without that pricing condition.
The $175 million loan cap is more than four times the $40 million limit under the Food Supply Chain program and far above the standard B&I limit. A regional beef plant or a modern seafood facility can potentially be financed in one guaranteed loan rather than pieced together across multiple structures.
A two-year deferral of principal and interest and terms up to 40 years can give a new or expanded plant time to reach full production before full debt service begins.
Processors often locate near livestock, ports, labor and highways, and those areas are not always rural by USDA's traditional definition. SPUR allows the project to locate where it makes the most business sense.
Banks retain only 10 percent of the exposure, can sell the guaranteed portion on the secondary market, and work under the familiar OneRD rules rather than a completely new framework. That combination may bring lenders to the table that would otherwise pass on a processing deal.
USDA has made at least $5 billion in loan authority available, and applications are accepted until funds run out. Well-prepared projects that move early may have the best opportunity to access the program.
Borrowers do not apply to USDA directly. A processor works with a participating lender, and the lender submits the guarantee request to Rural Development through the OneRD Guarantee process.
Applications are accepted year-round, beginning with the notice's publication on October 27, 2026, until the funds are used up. USDA is also funding technical assistance providers with expertise in processing and business planning to help applicants prepare.
A strong SPUR application looks a lot like a strong B&I application: a credible feasibility study, realistic projections, solid management, adequate equity, and inspection status lined up. Processors that start that work now will be better prepared when their lender is ready to move.
Guaranteed Lending Specialists helps borrowers and lenders structure, package and close USDA guaranteed loans. If you are weighing a meat, poultry or seafood processing project - or you are a lender with a processing client - we would be glad to talk through whether the USDA SPUR loan program fits.
Contact us to discuss your project.